 ·
5 minute read
The Autumn Budget 2026 rewards businesses that plan their workplace investment, not those that rush it. Chancellor John Healey's first Budget, delivered on 28 October 2026, improves tax relief on new investment from January 2027, keeps headline business tax rates where they were, and pushes the big defence decisions into next year's Spending Review.
For anyone weighing up an office, manufacturing, laboratory or defence fit-out, that adds up to a clear message: the next 12 months are for getting decisions right, so that projects are ready to move as soon as the better relief arrives in January.
Here is what changed, what didn't, and what we think it means for the way you plan your space.
Capital allowances: more relief, but timing matters
The headline for workplace investment is the main-rate first-year allowance rising from 40% to 50% for qualifying spend incurred on or after 1 January 2027. Full expensing, which gives companies a 100% deduction on qualifying new plant and machinery, stays in place.
The trade-off is a cut to the main writing-down allowance, from 14% to 12% from April 2027. Anything not claimed up front, including existing pool balances, will now be relieved more slowly.
What this means for a fit-out:
- The date you incur the cost matters. Spend before 1 January 2027 gets the current 40% rate; spend from January gets 50%. A project planned now and committed in the new year is well placed.
- Not everything in a fit-out is plant. Some elements qualify for allowances and some don't. How the work is classified decides how much relief you get and when.
- The rules favour new investment. The first-year allowance excludes second-hand assets, so specifying new plant and equipment as part of a fit-out can make a real difference.
In short, the Budget makes a well-planned 2027 project more tax-efficient than an unplanned one. Bringing your finance team and your fit-out partner together early is how you capture that value.
The economy: steadier now, tighter next year
The Office for Budget Responsibility upgraded growth for 2026 to 1.2%, but cut its 2027 forecast from 1.6% to 1.0% and raised expected inflation. Growth is forecast to recover to around 1.7% a year from 2028.
For finance directors, the more reassuring news is what didn't change. Corporation tax stays at 25%, and the headline rates of income tax, National Insurance and VAT were left alone. Employment costs are still rising, though: the National Living Wage goes up again, on top of last year's employer National Insurance increase.
Our view is that this is a Budget for careful commitment rather than caution. A slower 2027 makes it more important that every pound spent on space works hard, above all by giving people a real reason to come to work. The projects that make the case on those terms will get signed off.
Business rates are going local
The government plans to devolve all business rates revenue to local areas by the end of the decade. Over time, that could mean the cost of occupying a building varies more from place to place than it does today.
The Budget also extended small business rate relief, taking 70,000 more businesses out of rates altogether, though the biggest gains go to retail, hospitality and leisure. Most office and industrial occupiers will see little immediate change.
Where rates go local, location becomes a bigger part of the property equation. That strengthens the case for treating the thinking around stay or go as a proper decision rather than a lease-event reflex. The right answer depends on your people and how they use the space, and that is best understood before anyone draws a floorplan.
Defence: funded today, defined next year
The Budget fully funds the Defence Investment Plan, including a £4.7bn gap, partly by reprioritising capital spending across Whitehall. The Chancellor confirmed a target date of 2030 for spending 3% of GDP on defence, with the detail of how the UK reaches that, and NATO's 3.5% by 2035, to come at next year's Spending Review.
That creates a two-stage picture for the defence estate:
- Now: programmes already in the plan have firmer funding, which gives primes and their supply chains more certainty.
- After the Spending Review: the larger expansion of facilities, from secure offices to manufacturing and test space, is likely to follow once departmental budgets are set.
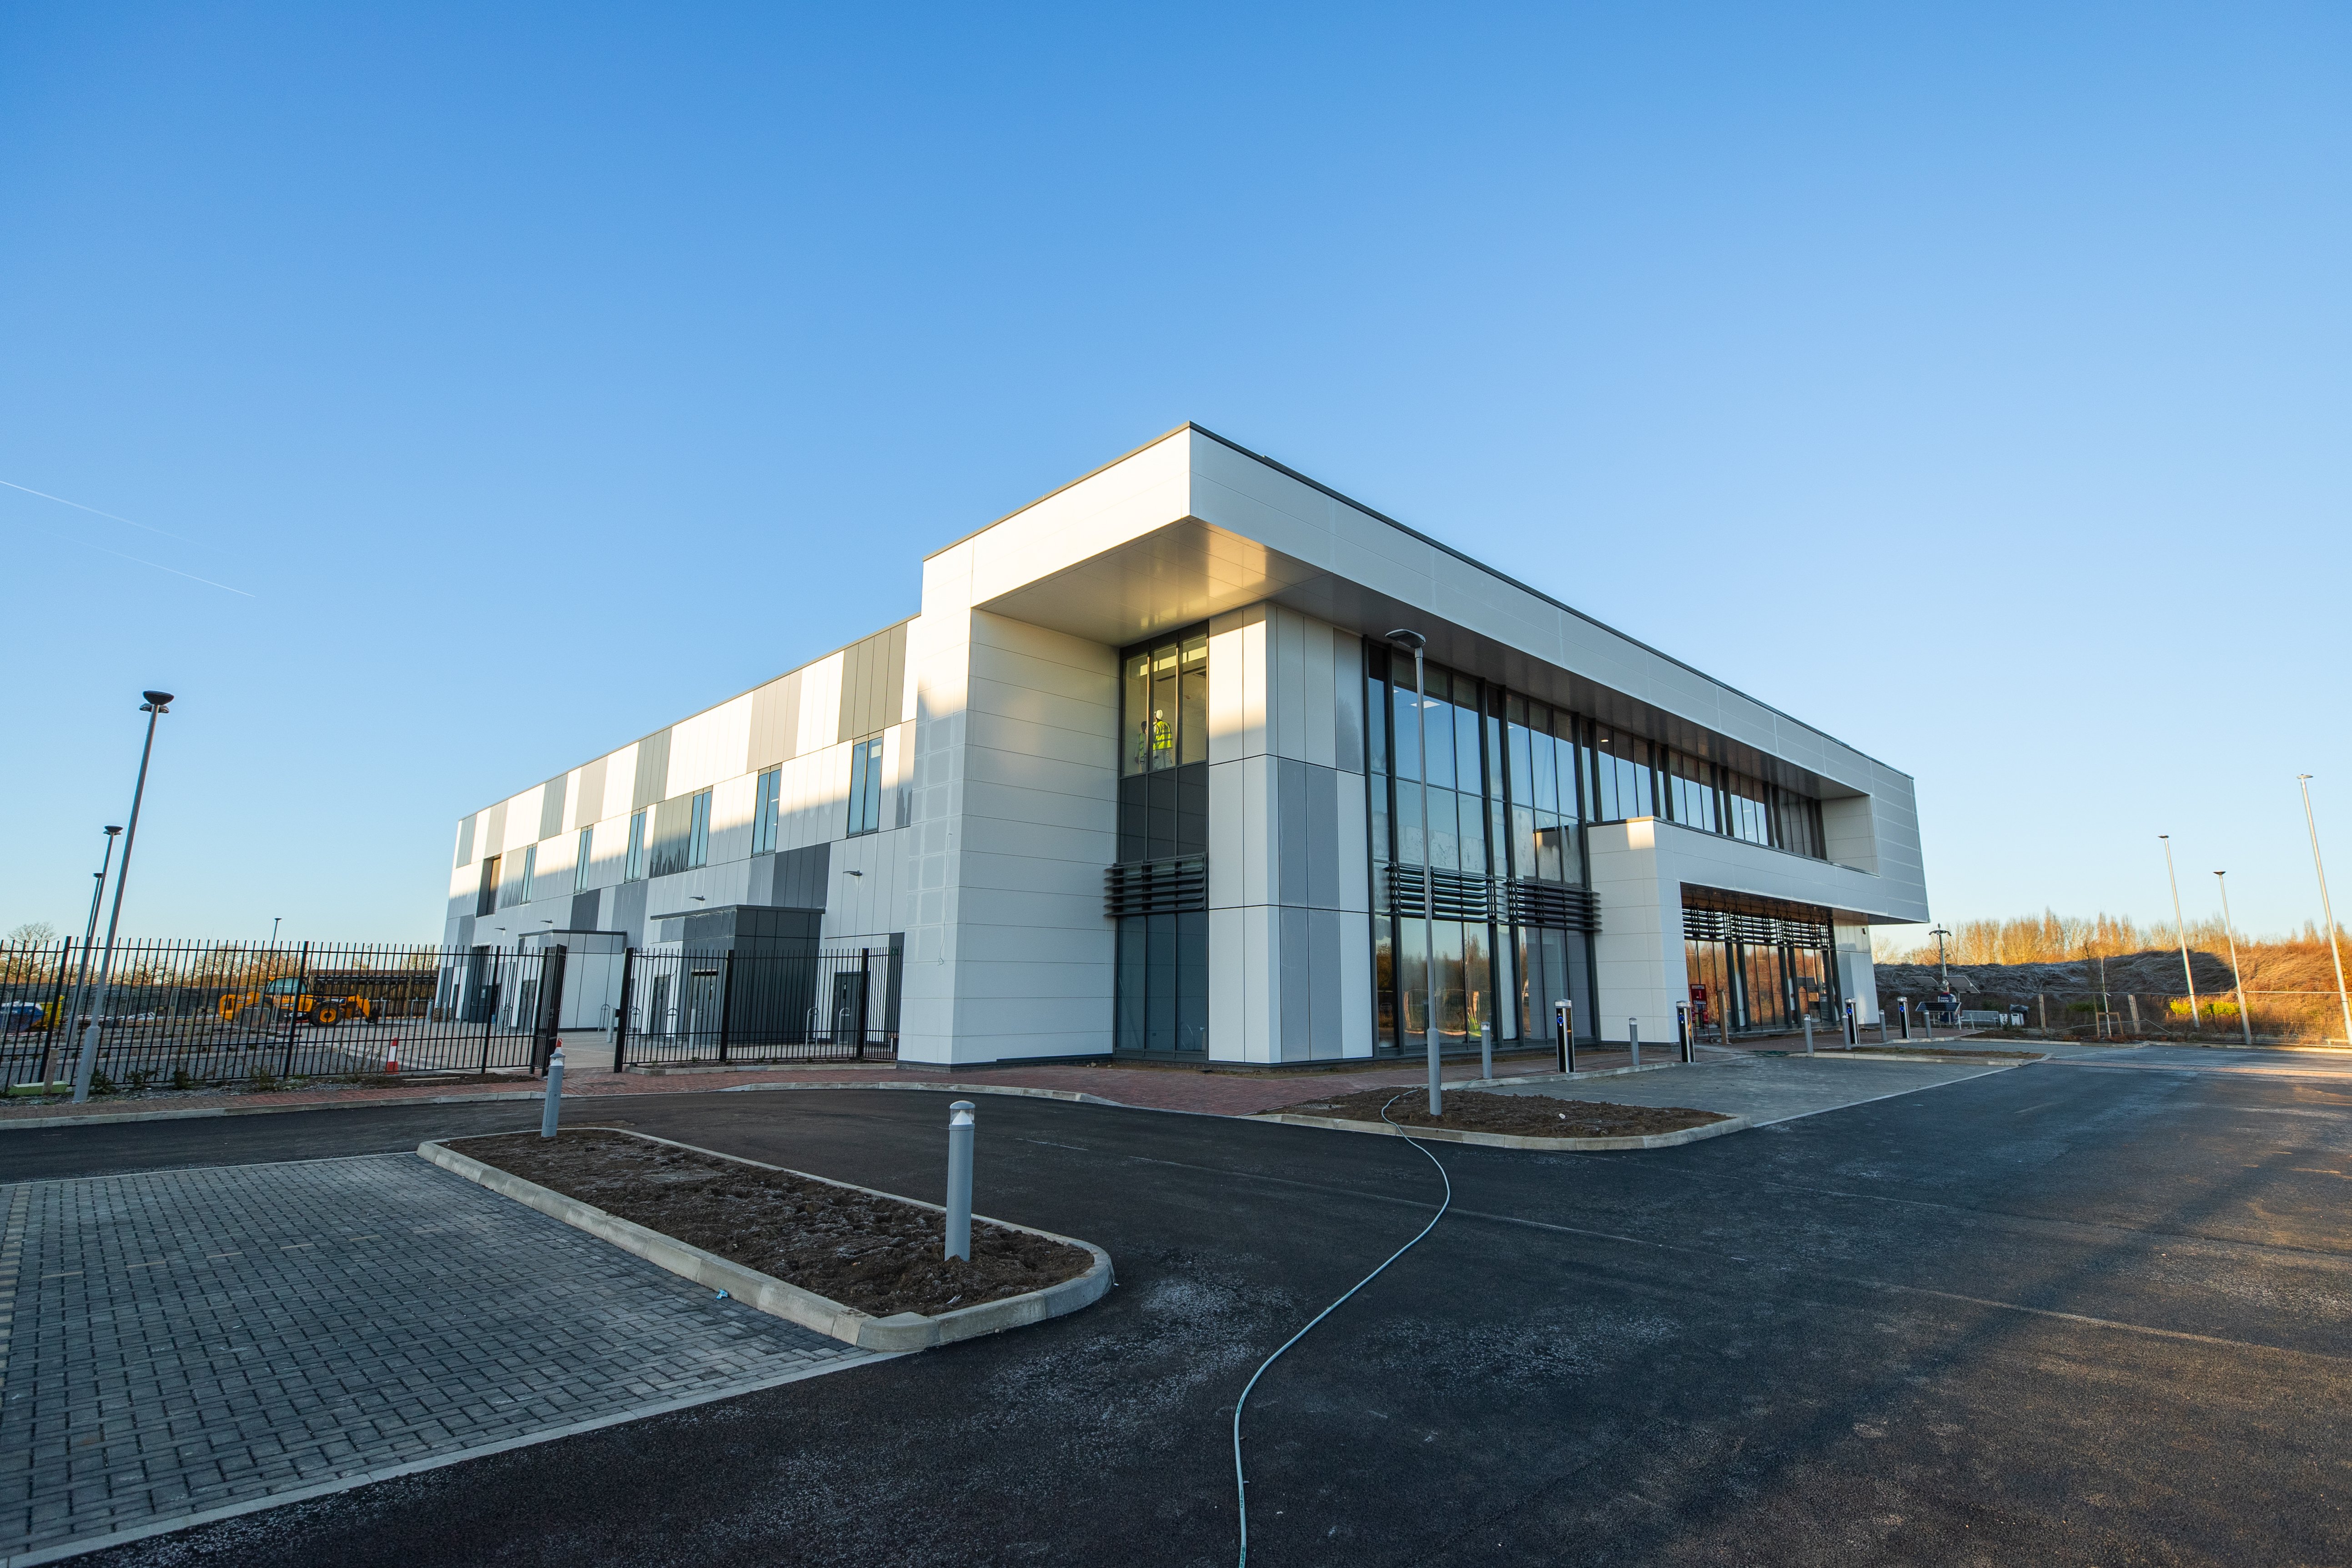
Defence facilities take time to get right, with security requirements built in from day one. Organisations that understand their estate needs before the Spending Review lands will be the ones ready to move when funding is confirmed. 2027 is the year to prepare.
London and the Southeast: more local power, more pressure on people
The Budget hands regional mayors more money and more control, including a share of business rates and some income tax revenue to fund major infrastructure. In London and areas with combined authorities, that points to more regeneration and public-sector projects over the coming years.
The pressure on people is rising too. With income tax thresholds frozen until 2030/31, more Southeast salaries are pulled into the higher-rate band, and living-cost squeezes land hardest where costs are already highest.
That matters for the workplace. When the commute costs more and take-home pay stretches less, the office has to earn the journey. Space that helps people do their best work is no longer a nice-to-have; it is part of how employers attract and keep people.
What it means by sector
|
Sector |
What the Budget changes |
What we'd do now |
|---|---|---|
|
Corporate headquarters |
Stable business tax rates, better first-year relief from January 2027, more local variation in rates over time |
Revisit the decision to stay or move, keeping 2027 costs and relief in view |
|
Advanced manufacturing |
Full expensing retained; 50% first-year allowance from January 2027; some energy-intensive firms get help with electricity costs through the British Industrial Competitiveness Scheme |
Plan plant and facility upgrades together so the tax treatment is designed in, not discovered later |
|
Industrial and warehouse |
Full expensing retained for new plant and machinery, with the 50% first-year allowance from January 2027; little change on business rates for larger industrial premises |
Time new warehouse equipment and building works so they make the most of the January 2027 relief |
|
Defence |
Defence Investment Plan fully funded; route to 3% by 2030 set out at the 2027 Spending Review |
Map estate needs and readiness ahead of the Spending Review |
|
Life sciences and laboratories |
No major lab-specific measures in the headline announcements |
Keep planning to long-term need; specialist space has long lead times whatever the cycle |
Our view: plan now, commit with confidence in 2027
This isn't a Budget that transforms the case for investing in your workplace. It is one that rewards organisations that know what they need and when they need it. Better relief arrives in January, defence funding clarifies after the Spending Review, and local rates will reshape location costs over the decade.
The businesses that benefit most will be the ones that use the coming months to understand what their space really needs to do, so that when they commit, they commit to the right thing.
Frequently asked questions
What did the Autumn Budget 2026 change for fit-out?
The main-rate first-year allowance rises from 40% to 50% for qualifying spend from 1 January 2027, full expensing stays, and the main writing-down allowance falls from 14% to 12% from April 2027.
Does all fit-out spending qualify for capital allowances?
No. Some elements of a fit-out qualify as plant and machinery, and others don't. Classification decides how much relief you receive and when, so take specialist tax advice early in the project.
When does the 50% first-year allowance start?
It applies to qualifying expenditure incurred on or after 1 January 2027.
What does the Budget mean for defence facilities?
The Defence Investment Plan is fully funded, and the route to 3% of GDP by 2030 will be set out at the 2027 Spending Review. Larger estate investment is likely to follow that review.
What does the Budget mean for laboratory and life sciences fit-outs?
The headline announcements include no lab-specific measures. The improved capital allowances still apply, and specialist lab equipment and services are more likely than general office fit-out to count as qualifying plant. Lab space also has long lead times, so planning early matters whatever the economic cycle.
What does the Budget mean for industrial and warehouse fit-outs?
Full expensing stays for companies investing in new plant and machinery, and the 50% first-year allowance applies from 1 January 2027. Some energy-intensive manufacturers will also get help with electricity costs through the British Industrial Competitiveness Scheme. Planning plant upgrades and building works together helps you get the tax treatment right from the start.
This article is for general information and isn't tax advice. Speak to a qualified adviser about your circumstances.
Sources
- HM Treasury: Budget 2026
- Office for Budget Responsibility: Economic and fiscal outlook, October 2026
- HM Treasury: Fiscal Devolution Roadmap
- House of Commons Library: Autumn Budget 2026, a summary
- Saffery: Autumn Budget 2026 for businesses
- Tax Policy Associates: Budget 2026, what it means
- CNBC: UK budget on energy, banks and defence
- LBC: Key points from the Budget
- Professional Adviser: Income tax threshold freeze remains until April 2031